International Financial Centre targets first transactions in November
VOV.VN - The Vietnam International Financial Centre is targeting operational readiness in October and its first transactions in November 2026, as authorities step up efforts to complete institutional arrangements, strengthen financial supervision and attract participating institutions and investors.
The plan was discussed at the fourth meeting of the Vietnam International Financial Centre Executive Council in Hanoi on October 22 to review progress and identify the work needed to meet the timeline.
Completing the conditions for operation

According to the Ministry of Finance, the Government has been presented with proposals concerning the consolidation of the Executive Council, a development plan for the International Financial Centre through 2035, and the Centre’s operating regulations. The operating authorities at the two locations – Ho Chi Minh City and Da Nang - have also agreed on forms for registering and recognising members.
Preparations have extended to staffing, funding, offices and technological infrastructure, with the two localities approving staffing arrangements and allocating the necessary resources. Investment promotion activities have taken place in several countries, while banks, securities companies, asset management organisations and investors have signed memoranda of understanding, made commitments or submitted membership applications.
Work is also under way to identify transactions that could be launched early. Ministry of Finance leaders have held direct discussions with commercial banks and financial institutions to assess potential transactions. The operating authorities in Ho Chi Minh City and Da Nang have reported on implementation progress.
To ensure consistent operations across the two locations, the Ministry of Finance has proposed standardising business procedures, establishing a one-stop mechanism, aligning membership recognition criteria and reporting requirements, improving coordination between the locations, and clarifying the division of financial products between the two cities.
Deputy Prime Minister Nguyen Van Thang, who chaired the meeting, commended the progress made by ministries, agencies and the two cities, particularly the operating authorities. He requested that the Ministry of Finance, the State Bank of Vietnam and other relevant bodies coordinate closely, implement the Government leadership’s directives decisively, maintain the quality and pace of work, and resolve overdue tasks and outstanding obstacles.
Ensuring effective oversight and launching initial transactions
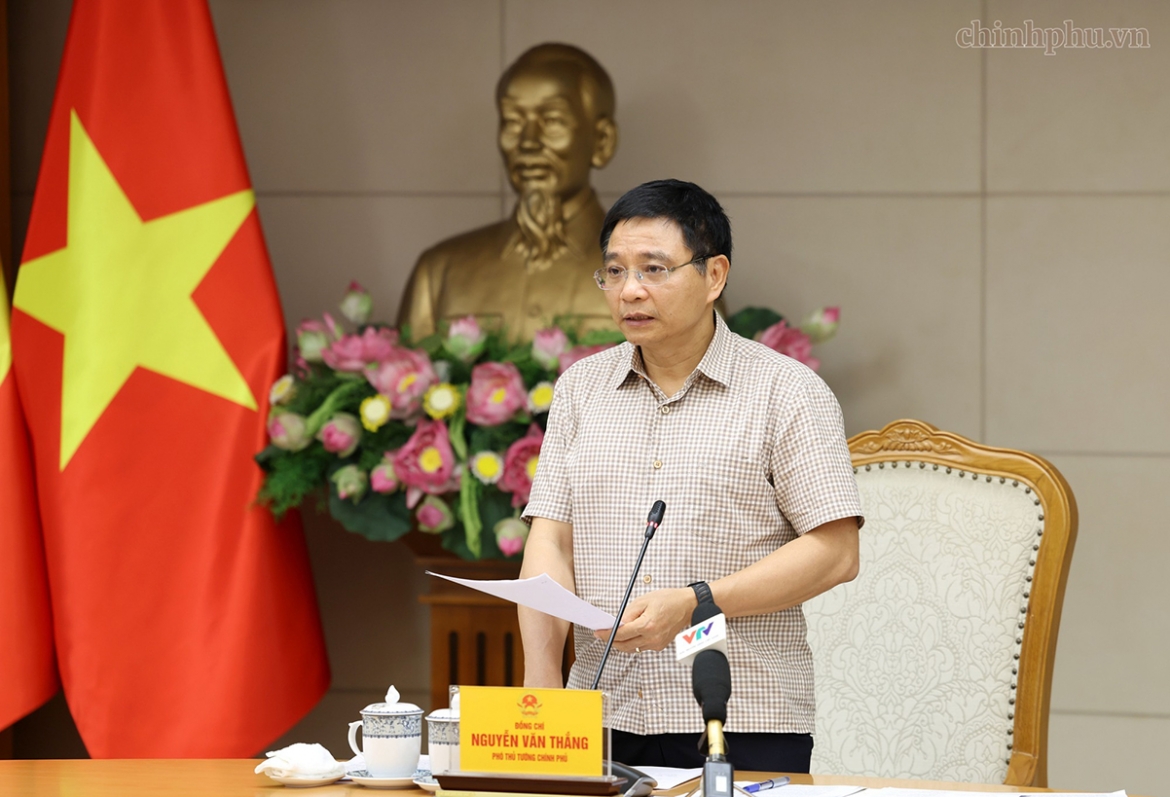
Meeting the November target will also depend on clear institutional responsibilities and effective financial supervision. The Deputy Prime Minister instructed the Ministry of Finance to guide and monitor relevant ministries, agencies, localities and the operating authorities in implementing the Centre’s activities in line with existing directives.
The Ministry of Finance, working with the State Bank of Vietnam and relevant agencies, must define the powers and responsibilities of each authority, avoid overlapping mandates and ensure that the supervisory authority is operational before substantive transactions begin. Progress in establishing a dedicated arbitration centre and a specialised court must also be reported and accelerated.
Alongside these institutional preparations, the Centre needs financial products and transactions that can be implemented in practice. The Deputy Prime Minister said products traded at international financial centres could be considered for Vietnam if they suited local conditions and the country’s capacity to manage risks.
Initial efforts should focus on transactions where potential providers and recipients of capital have already established contact, particularly products that mobilise and supply medium- and long-term funding. For each proposed product, the Ministry of Finance must clarify implementation responsibilities, required policy measures, approval procedures and appropriate supervision arrangements.
The Deputy Prime Minister called for a flexible approach, with the authorities ready to review proposals and resolve emerging obstacles rather than allowing regulatory gaps to delay products that are ready for implementation.
The operating authorities in Ho Chi Minh City and Da Nang are tasked with completing the necessary conditions by the end of October 2026. They must also engage directly and proactively with financial institutions and investors to attract members and strive to launch transactions in November, while ensuring compliance with the law and financial safety.
To keep preparations on schedule, Executive Council members are to direct the agencies under their authority to carry out assigned tasks and issue guidance documents within their remit, ensuring both timely delivery and quality. Any difficulties or shortcomings must be reported promptly to the Executive Council for consideration and resolution.
The aim is to prevent regulatory obstacles from holding back products that are ready for implementation and to ensure that the Centre can move towards its first transactions on schedule, with effective oversight and safeguards in place.
Da Nang International Financial Centre joins sustainable finance network
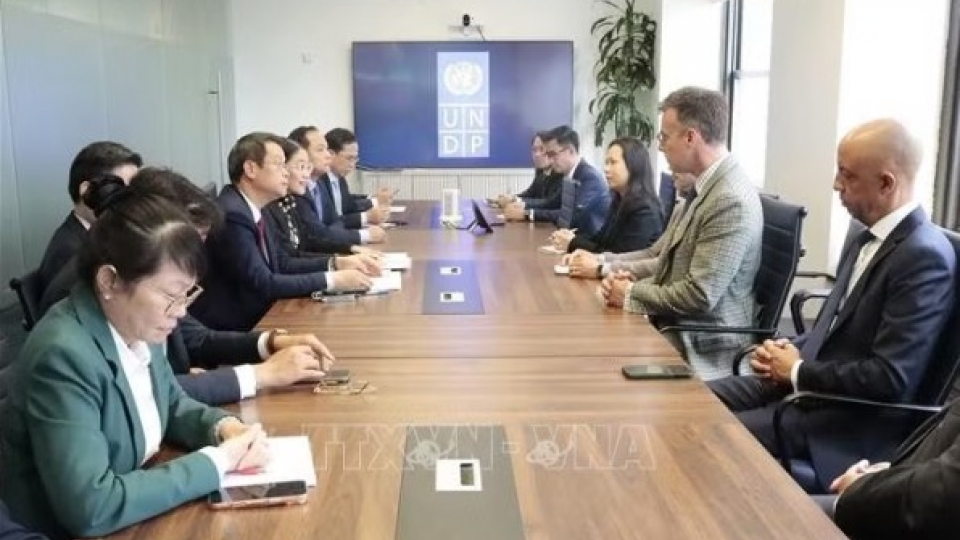
VOV.VN - A working delegation from the central city of Da Nang led by Chairman of the municipal People's Committee Nguyen Manh Hung held a working session with the United Nations Development Programme (UNDP) in New York on September 25.